Red-Dyed Diesel on the Highway: What the Order Defers, and What It Doesn't
The order defers the 24.4-cent federal tax on diesel through December 31, 2026. Deferred is not forgiven, and state rules vary by state.
On October 5, 2026, the President signed an executive order on diesel fuel. It is short, it is narrow, and it is being described in a way that will cost some readers money if they act on the description rather than the text. The order covers one specific product — red-dyed diesel, the off-road fuel that is normally sold untaxed — and it allows that fuel to be used on public highways through the end of the year. It does not repeal a tax. It defers one. Four days later, on October 9, it was published as Executive Order 14435 — and the announcement the order itself required, from the IRS, had still not appeared.
That distinction is the whole article. Here is what the order does, what it leaves alone, and what a reader who buys diesel should actually do.
What the order directs
Three things, all of them keyed to a window that runs from October 5 through December 31, 2026. Sections 5 through 8 then hand work to four other officials without changing the substance.
The tax is deferred, not forgiven. The order directs the Treasury Secretary to determine, within five days, whether relief is authorized under 26 U.S.C. § 7508A, and — if it is — to defer payment of the taxes “imposed by 26 U.S.C. 4041(a)(1)(A) or by 26 U.S.C. 4041(b)(1)(B)” for fuel used during the window, with no penalties, interest or additions to the tax. Those are the order’s own words, and they are worth reading carefully, because the citation is not a clean one. § 4041 has no subsection (b)(1)(B): subsection (a)(1)(A) imposes the tax on any liquid other than gasoline sold for use or used in a diesel-powered highway vehicle, while subsection (b) is the off-highway business-use exemption, (c) covers certain liquids used as aviation fuel, and (d) is the Leaking Underground Storage Tank trust-fund tax. The “or 4041(b)(1)(B)” in the order appears to be a drafting error, and a reader should not read it as identifying a second, separate tax on dyed fuel. The reason is structural: dyed fuel is precisely the product that is already outside § 4041(a)(1)(A), because that paragraph taxes liquid fuel “sold … for use as a fuel in [a] diesel-powered highway vehicle,” and dyed diesel is sold for off-road use. Nothing in the order, and nothing in the coverage, explains what the second citation was meant to reach. So the citation the Secretary actually relies on is a question for the implementing guidance, and it is the first line to read when the guidance appears.
The dyed-fuel penalty is waived for the same window. The order directs the Secretary to have the IRS announce that it will not impose the penalty under 26 U.S.C. § 6715(a)(1) or (a)(2) when dyed diesel is sold for use or used on the highway between October 5 and December 31, 2026 — and that the announcement will also address relief from penalties for failing to make semimonthly deposits of that tax.
The order asks for implementation, not for repeal. A further section directs the Secretary to issue guidance identifying who qualifies, the conditions, the dates, and the date by which the postponed taxes must be paid. Another directs the Secretary to explore avenues, “including legislation,” to eliminate the deferred obligation. Exploring is not doing. Two sections reach other agencies: the order directs the Secretary of Agriculture to coordinate with agricultural cooperatives and rural fuel distributors “to ensure adequate distribution of dyed diesel” in high-demand areas and to encourage state action, and directs the Secretary of Transportation, acting through the Federal Motor Carrier Safety Administration, to keep “all compliance enforcement measures, including audits, inspections, and monitoring programs” running. A third provision, with no counterpart in the press coverage, tells the Secretary to assess how the IRS should allocate resources to inspecting vehicle fuel tanks and sampling fuel during the relief period and to announce that decision publicly. Read together, sections 5 through 7 describe a system that is being told to make the fuel available and to keep checking who is using it.
The condition nobody is quoting
Section 2 of the order is conditional, and the condition is worth reading twice. It tells the Secretary to determine whether relief is authorized under § 7508A, including whether a qualifying event has occurred and which taxpayers were affected. Only if the answer is yes does the deferral follow.
That matters because § 7508A is not a general grant of authority to suspend a tax any time the Secretary thinks the price is too high. It is the provision that lets the Secretary postpone deadlines for taxpayers affected by a federally declared disaster, a significant fire, or terroristic or military actions — and, in a separate subsection, for a state-declared disaster on the written request of a governor. The Secretary, not the order, is the one who decides whether that ground exists here.
One consequence of the conditional wording is easy to miss, and it has spread through the coverage. The order does not say the deferral reaches only dyed fuel. It directs the Secretary to defer the taxes cited in § 4041 for fuel used in the window — and § 4041(a)(1)(A) is the tax on any liquid other than gasoline sold for use or used in a diesel-powered highway vehicle, which is the 24.4-cent tax that clear highway diesel already carries. The dyed-fuel penalty relief is a separate requirement, in the next subsection, and it exists precisely because dyed fuel is what is normally barred from the road. On a plain reading the text therefore reaches two different groups of taxpayers: the deferred tax can apply to highway diesel, and the penalty relief answers the separate problem that the fuel most likely to be substituted for it is dyed. Some outlets — the Associated Press among them, which described the order as deferring “the $0.24 federal tax per gallon of regular diesel” — read it the other way, as covering dyed fuel only. Both readings are in circulation. The guidance is what will settle it, and it is worth knowing which reading you are acting on before you buy.
What was still missing when the order was published
On October 9, 2026 the order appeared in the Federal Register as Executive Order 14435, at 91 Fed. Reg. 64747, under the title Emergency Tax Relief on Diesel Fuel. Reading the published text in full confirms the parts described above — the five-day deadlines, the § 7508A condition, the penalty relief, the section that only authorizes the Secretary to “explore” forgiveness — and adds three that the announcement did not emphasize: the fuel-tank inspection review, the Agriculture Department’s distribution role, and the instruction that FMCSA keep all its enforcement measures running.
What publication did not bring is the part a driver or a farmer needs. As of the same day, the Internal Revenue Service had published no announcement under the order. The IRS newsroom’s most recent release is still IR-2026-120, dated October 7, 2026 — a release about a whistleblower partnership with the United Kingdom, not about fuel. The order required the announcement within five days of signing, which would be October 10. At publication there was no announcement, no Treasury guidance, and no public determination on whether a qualifying event for § 7508A exists — the condition the entire deferral hangs on.
That is the operative fact for anyone deciding anything this month. The order grants no relief by itself. It directs an official to consider granting relief, and the official’s statement has not appeared.
That check has now been repeated a day later, and the answer has not changed. On October 10, 2026 — the day the order’s own five-day clock ran out — the announcement still had not been published. The IRS newsroom’s newest release remained IR-2026-120 of October 7, about a whistleblower partnership with the United Kingdom, and the Federal Register’s presidential documents carried nothing from the Treasury under this order. So as of this revision the deferral remains conditional on a determination that has not been made public, and the conditions the guidance is supposed to supply — who qualifies, on what terms, and when the postponed tax comes due — are still unknown.
The arithmetic the savings claims depend on
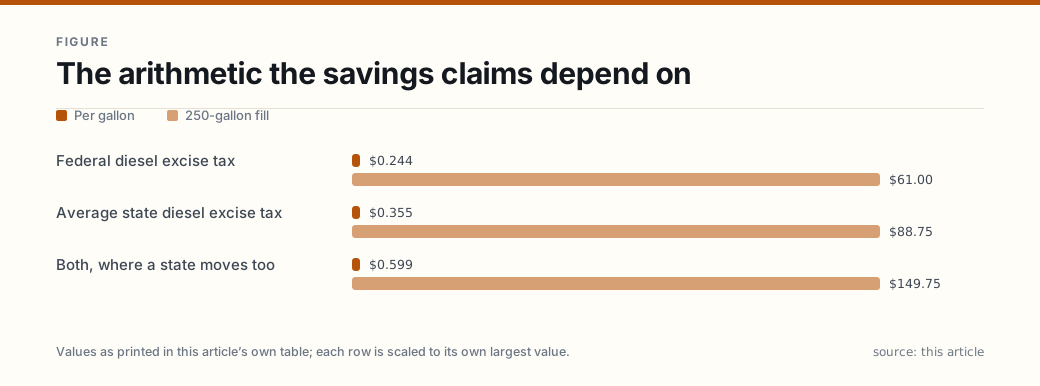
The federal excise tax on diesel used on the highway is 24.4 cents a gallon. Set that against a 250-gallon fill, which is roughly what a tractor-trailer takes:
| Item | Per gallon | 250-gallon fill |
|---|---|---|
| Federal diesel excise tax | $0.244 | $61.00 |
| Average state diesel excise tax | $0.355 | $88.75 |
| Both, where a state moves too | $0.599 | $149.75 |
The federal piece alone is $61, not the “over $100 per refill” in the announcement — reaching that figure requires the state to suspend its own tax as well. The order cannot do that. State diesel taxes average about 35.5 cents a gallon, and they are untouched by a federal order; what the order does is direct the White House Office of Intergovernmental Affairs to encourage states to align. Ten states had already taken their own steps between September 23 and October 2, 2026, before the federal action.
Two more things fall out of the table. The federal tax is roughly 4% of the national average on-highway diesel price for the week of October 5, 2026 — $6.199 a gallon, per the Energy Information Administration. And that price is already coming down on its own: it was $6.529 in the week of September 21, and AAA’s national average hit a record of $6.53 on September 22. The week-to-week decline since the September 21 week has run at about 2% a week, for a cumulative move of about 5% over the two weeks to October 5 — larger than the federal tax being deferred, and in the other direction.
That is the substance of the disagreement over the order. Supporters describe it as immediate relief at harvest, in a fuel market where the average on-highway price for the week of October 5 was $2.488 a gallon higher than the same week a year earlier; critics call it a small and late measure that leaves the underlying supply problem untouched. Two people quoted in the press coverage, both of whom work in the fuel market, put the skeptical case: GasBuddy’s Patrick De Haan called it “not really a needle-mover,” noting that making dyed fuel more available across state lines is harder than it sounds, and New Jersey fuel supplier John Tirado called it “a Band-Aid” that “comes late.” The text supports the narrower reading of what changed: it alters the tax timing on one fuel, for one defined window, and it cannot bind a state.
The penalty being stepped around, and when it comes back
It is worth being precise about what the relief is relief from, because the ordinary rule is not a slap on the wrist. Under § 6715, using dyed fuel for a taxable purpose carries a penalty of the greater of $1,000 or $10 for each gallon of dyed fuel involved, on each act. For a 250-gallon fill that is $2,500, not $1,000.
Three details make it sharper. The $1,000 floor is multiplied by the number of prior penalties imposed on that person, so a repeat violation climbs. Officers, employees and agents of a business who willfully participated are jointly and severally liable with the entity. And after a third or subsequent violation confirmed by chemical analysis, there is no administrative appeal except on a claim of fraud or mistake in the analysis, or of a math error in the penalty.
Now read the window again. The relief covers fuel used from October 5 through December 31, 2026. Dyed fuel used on the highway on October 4 or on January 1, 2027 falls outside it. A reader who fills with dyed diesel in December and again in January has moved from a waived penalty back to the ordinary one, at $10 a gallon, with no notice. The order is also silent on a condition the IRS attached to its earlier regional relief of the same kind: in the 2024 dyed-diesel relief after Hurricane Helene, the relief for a vehicle operator was available only if the operator or the seller paid the 24.4-cent tax that applies to highway diesel. Whether the 2026 announcement carries the same condition is exactly what the guidance will say, and it is the first thing to read.
The sellers are being told not to sell
An order can authorize a sale; it cannot make one happen. On October 7, 2026, two national fuel-retail trade groups — the Society of Independent Gasoline Marketers of America (SIGMA) and the National Association of Truck Stop Owners (NATSO) — advised their members against selling dyed diesel for highway use under the order. Their stated reasons, as reported by NBC News and The Hill: “the tax is still owed, so there’s limited upside” — the deferral defers, it does not cancel — and a practical one, that “residual dye lingers in tanks and fuel systems,” which matters to a retailer whose other customers do not want red fuel in their tanks. A third group, the Energy Marketers of America, told stations to “proceed with caution,” making the same point this article has made since the order was signed: “Whether relief is available, whom it covers, and on what conditions depend on Treasury determinations and guidance not yet issued,” and “deferral is not forgiveness.” The White House, through a spokesperson, maintains the order will “quickly cut diesel costs” with savings “of as much as $100 per fill.”
Read together, the trade-group guidance describes a supply side that is likely to stay cautious until the IRS announcement and Treasury guidance exist. For a driver, that means the pump at the truck stop may not have dyed diesel at all in the meantime, whatever the fact sheet promises — the buying side of the transaction is being warned that the selling side sees limited upside.
One date discrepancy is worth recording, because readers are asking and because the order’s publication now settles it. The Hill reported on October 7 that a White House official described the enforcement halt as running “from Oct. 5 to Dec. 13,” while the order’s own text runs the relief window through December 31, 2026, and the White House spokesperson quoted in the same report said the tax is deferred “through the end of the year.” The order as published in the Federal Register on October 9 — 91 Fed. Reg. 64747 — runs the window and the penalty relief to December 31, 2026 in both places, and carries no December 13 date anywhere. The December 13 remark is unexplained and does not come from the order. A reader planning around mid-December should plan to December 31 as written, and re-read the guidance when it appears.
Who this actually changes things for
Honestly: not most readers of this page.
- Farmers and agricultural haulers. This is the group the order is aimed at, and the one that asked for it. Fuel used in a tractor or a combine is already nontaxable; the change is about fuel used in the trucks that move the crop, which is the part that was legally exposed.
- Trucking companies and diesel fleets. The saving is real but small against a $6.20 gallon, and it depends on being able to buy dyed fuel in volume — which, as of October 7, the major truck-stop and fuel-marketer trade groups are advising their members not to supply (see above). Dyed diesel is normally a bulk and cardlock product, not something sold at the retail pump on the corner.
- Owners of diesel pickups, vans and motorhomes. You may now be within the federal relief if your state aligns, and many states have not — which is why the state check on your own state’s rules is the operative step, not the federal one.
- Everyone else. Diesel is a freight input, so any effect on the price of goods would be indirect and slow.
If someone offers to help you claim it
A federal tax break of this shape reliably attracts two things: bad advice and outright fraud. Keep these four rules.
- There is no refund in this order. Nothing in it pays anyone money. Anyone selling a service to “claim your diesel tax rebate” is not describing this order.
- The IRS does not call, text or email demanding immediate payment or personal information, and it does not ask you to pay a tax with gift cards, wire transfers or cryptocurrency. Government contact about a tax matter arrives by mail and can be verified against your own account at irs.gov.
- Verify the counterparty, not the paperwork. A seller offering “tax-free diesel” outside normal commercial channels is worth walking away from. Confirm fuel-tax questions with the IRS or a tax professional, not with the person selling the fuel.
- Report it. Fraudulent tax schemes go to the FTC at reportfraud.ftc.gov and to the IRS.
What to do, and what to watch
- If you defer tax under this relief, set the cash aside. The deferral is a timing change. The order’s own guidance section contemplates a date by which the postponed taxes are paid, and that date has not been published.
- Check your state before you buy. State diesel taxes and state enforcement are separate. A federal waiver is not a state one.
- Read the IRS announcement when it appears, and read the conditions rather than the headline. The order’s five-day deadline for that announcement fell on October 10, 2026, and as of that day it had still not been published.
- Read the Treasury guidance when it appears — it is the document that has to name who qualifies, the conditions, and the date the deferred tax comes due.
- Do not assume the order is self-executing. Nothing in it obliges a fuel seller to sell, and the two national fuel-retail trade groups were advising their members against selling dyed diesel for highway use when the order was published.
- Do not plan a January fill around this. December 31, 2026 is the end of the relief as written.
The supply side of the same problem is a separate instrument with a later end date. On October 9, 2026 the Treasury’s Office of Foreign Assets Control issued Russia-related General License 135, authorizing transactions related to the sale, delivery, offloading and importation of diesel of Russian origin — including into the United States — through 12:01 a.m. eastern daylight time on April 7, 2027. That license moves a legal barrier; this order moves money in time, and neither of them creates a barrel. It is covered in The Russian diesel license: Authorized is not delivered.
The general lesson is the one that applies to most tax relief announced with a deadline: the announcement tells you what is being given, and the operative document tells you when it has to be given back. Our walkthrough of the rest of the year’s real deadlines is in Year-End Money Moves, and the network’s government resources directory collects the primary sources behind both.
This article is general information about a change in federal tax timing, not tax advice, and it is not a substitute for advice about your own situation. Federal fuel tax treatment is national; state diesel taxes and state enforcement vary by state, so check the rules where the vehicle is registered and where it is driven. It is AI-written and independently AI-reviewed before publication; the review standard and this article’s findings are recorded in the network’s editorial review log.
Frequently asked questions
- Is the federal diesel tax canceled?
- No. The order directs the Treasury Secretary to defer payment of the excise tax on highway use of dyed diesel for fuel used from October 5 through December 31, 2026, without interest or penalties. It does not cancel the tax. A separate section tells the Secretary only to explore avenues, including legislation, to eliminate the deferred amounts — which means the obligation still exists until something else removes it. Set the money aside rather than spending it.
- Can I legally put red-dyed diesel in my truck now?
- Not yet on the federal side — the order directs the IRS to announce that it will not impose the dyed-fuel penalty for diesel sold for use or used on the highway during October 5 through December 31, 2026, and that announcement had still not been published when the order's own five-day deadline passed on October 10, 2026. That relief runs to the federal penalty; it does not change state law, and states set their own diesel taxes and their own enforcement. Check your state before you fill, and read the IRS announcement when it is published, because its conditions are not yet known.
- Does this lower the price at the pump?
- Only for fuel actually sold as dyed diesel, and only if the seller passes the tax saving through. The federal excise tax on diesel is 24.4 cents a gallon, which is about 4% of the national average price for the week of October 5, 2026. Dyed diesel is normally a commercial and agricultural product sold through bulk and cardlock channels rather than at ordinary retail pumps, so most drivers will not see a pump price change at all.
- Will truck stops actually sell dyed diesel now?
- Not necessarily. On October 7, 2026, the truck-stop and fuel-marketer trade groups SIGMA and NATSO advised their members against selling dyed diesel for highway use under the order — the tax is still owed, the deferral is not forgiveness, and residual dye contaminates tanks and fuel systems — and the Energy Marketers of America told stations to proceed with caution until Treasury guidance exists. Assume the pump may not have it until the IRS announcement and guidance appear.
Sources
Each source is a primary or official reference, checked before publication. Links open the original.
- The White House — 'Emergency Tax Relief on Diesel Fuel', executive order signed October 5, 2026 (directs deferral of tax under 26 U.S.C. 4041(a)(1)(A) or 4041(b)(1)(B) for the period October 5 – December 31, 2026, and directs the IRS to announce relief from 26 U.S.C. 6715 penalties) — whitehouse.gov/presidential-actions/2026/10/emergency-tax-relief-on-diesel-fuel/
- 26 U.S.C. § 4041 — 'Imposition of tax' (read this run: subsection (a)(1)(A) imposes the tax on any liquid other than gasoline sold by any person to an operator of a diesel-powered highway vehicle for use as a fuel, or used by any person as a fuel in such a vehicle unless there was a taxable sale; there is no subsection (b)(1)(B) — (b) is the off-highway business-use exemption, (c) covers certain liquids used as aviation fuel, and (d) is the Leaking Underground Storage Tank trust-fund tax) — law.cornell.edu/uscode/text/26/4041
- Federal Register — Executive Order 14435, 'Emergency Tax Relief on Diesel Fuel', published October 9, 2026, 91 Fed. Reg. 64747 (Vol. 91, No. 195, FR Doc. 2026-20855) — the signed order as printed, including the five-day deadlines in section 2, the section 5 direction to assess how the IRS allocates fuel-tank inspection and fuel-sampling resources and to announce that determination publicly, the section 6(b) instruction that FMCSA continue all audits, inspections and monitoring programs, and the section 7 direction to the Secretary of Agriculture on dyed-diesel distribution — federalregister.gov/documents/2026/10/09/2026-20855/emergency-tax-relief-on-diesel-fuel
- The White House — 'Fact Sheet: President Donald J. Trump Promotes Diesel Affordability', October 5, 2026 (the administration's description of the order and its projected savings) — whitehouse.gov/fact-sheets/2026/10/fact-sheet-president-donald-j-trump-promotes-diesel-affordability/
- Internal Revenue Service — IR-2024-254, 'IRS granting dyed diesel penalty relief as a result of Hurricane Helene', October 1, 2024 (the same penalty-relief mechanism on a regional basis; states the 24.4-cent-per-gallon highway diesel rate and the semimonthly deposit relief) — irs.gov/newsroom/irs-granting-dyed-diesel-penalty-relief-as-a-result-of-hurricane-helene
- 26 U.S.C. § 7508A — 'Authority to postpone certain deadlines by reason of Federally declared disaster, significant fire, or terroristic or military actions' (the provision the order invokes, including the requirement that the Secretary determine that a qualifying event occurred) — law.cornell.edu/uscode/text/26/7508A
- 26 U.S.C. § 4041 — 'Imposition of tax' (subsection (a)(1)(A) taxes liquid fuel sold for use or used in a diesel-powered highway vehicle) — law.cornell.edu/uscode/text/26/4041
- 26 U.S.C. § 6715 — 'Dyed fuel sold for use or used in taxable use, etc.' (penalty of the greater of $1,000 or $10 per gallon, increased for repeat violations; joint and several liability for officers and employees) — law.cornell.edu/uscode/text/26/6715
- U.S. Energy Information Administration — Gasoline and Diesel Fuel Update, release of October 6, 2026 (U.S. on-highway diesel, week of October 5, 2026: $6.199 per gallon, against $6.529 in the week of September 21, 2026) — eia.gov/petroleum/gasdiesel/
- Internal Revenue Service — Publication 510, Excise Taxes (how fuel excise tax is reported and paid, including semimonthly deposits) — irs.gov/publications/p510
- Internal Revenue Service — 'Tax Scams and Consumer Alerts' (how the IRS contacts taxpayers about a tax matter, and how to report an impersonation attempt) — irs.gov/newsroom/tax-scams-consumer-alerts
- Federal Trade Commission — reportfraud.ftc.gov, the FTC's consumer fraud reporting portal — reportfraud.ftc.gov
- Internal Revenue Service — Newsroom, releases index (checked October 9 and again on October 10, 2026, the day the order's own five-day deadline fell: the most recent release is still IR-2026-120 of October 7, 2026, about a whistleblower partnership with the United Kingdom tax authority — no dyed-diesel or fuel-tax announcement under the order has been published) — irs.gov/newsroom
- Federal Register — Executive Orders index (checked October 9 and again on October 10, 2026 for the 2026 sequence, which runs to EO 14435, the diesel order published October 9, 2026; no Treasury determination or guidance under the order had appeared) — federalregister.gov/presidential-documents/executive-orders
- Associate Press — 'Trump's executive order on dyed diesel will offer little relief, farmers and truckers say' (October 2026): reads the order as deferring "the $0.24 federal tax per gallon of regular diesel" — a reading this article records as contested, since the order cites 26 U.S.C. 4041(a)(1)(A) or 4041(b)(1)(B) without the second citation corresponding to any provision of § 4041 — apnews.com/article/diesel-prices-fuel-farmers-agriculture-trump-9f01941a843fbd8ba64240e296c43f1b
- The Hill, 'Truck stops warned against red-dyed diesel sales: “Limited upside”', October 7, 2026, 11:18 a.m. ET (the SIGMA/NATSO member note and Energy Marketers of America's 'proceed with caution' and 'deferral is not forgiveness', both as reported there with attribution to NBC News; the White House official's description of the enforcement halt as running from October 5 to December 13; spokesperson Taylor Rogers's statement) — thehill.com/policy/transportation/6133775-industry-warns-truck-stops-dyed-fuel/
- CNN, 'Trump signs executive order aimed at lowering diesel prices', October 5, 2026 (AAA's record average of $6.53 on September 22; the ten states that acted before the order per ClearView Energy Partners; the average state diesel tax of 35.5 cents a gallon; and the analyst comment from GasBuddy's Patrick De Haan and New Jersey fuel supplier John Tirado) — cnn.com/2026/10/05/business/trump-diesel-prices-executive-order